Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
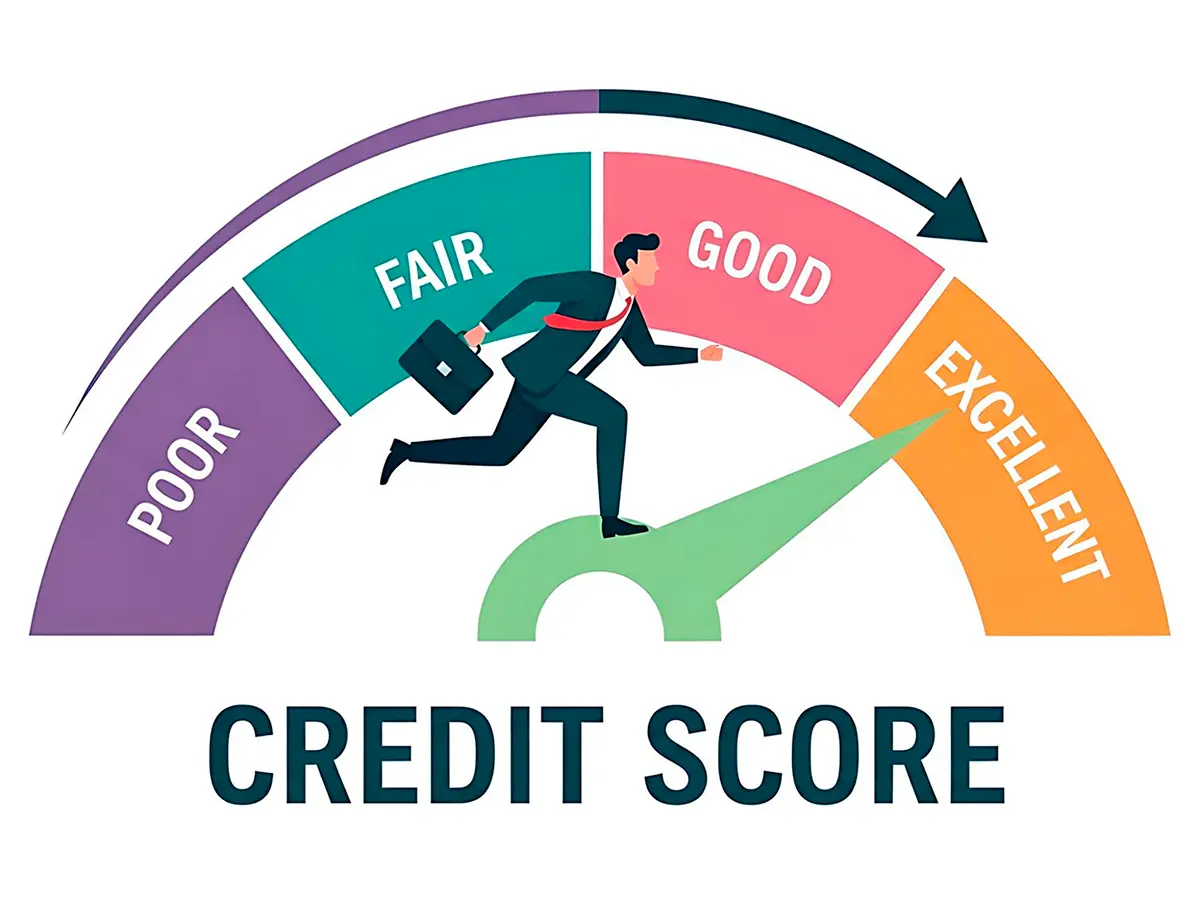
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
credit repair companies in miami fl for clear next steps
Credit turns on trust, time, and documentation. The best credit repair partners in Miami don't sell miracles; they organize facts, challenge errors, and coach habits that move a score from fragile to durable. Think of them as navigators in a busy port - useful for charting a course, but the captaincy remains yours.
What these firms actually do
Good teams start with your three-bureau reports, map discrepancies, and prioritize high-impact fixes. They dispute unverifiable negatives, correct mixed-file issues common in dense metro areas, and escalate with furnishers when evidence supports you. They also help you stack small wins - lower utilization, healthier mix - while the disputes cycle through.
- Audit and triage: Personal info cleanup, duplicate collections, date errors.
- Dispute management: Letters and e-disputes paced to 30 - 45 day bureau cycles.
- Furnisher follow-up: Asking original creditors to verify or update.
- Rebuild plan: Secured cards, credit-builder loans, utilization strategy.
- Education: What to do - and not do - while you're in the process.
Signals a Miami firm is credible
Look for clear pricing, written agreements, and compliance with the Credit Repair Organizations Act. Pros set expectations, not traps. They won't promise score points, deletions on accurate items, or one-week turnarounds.
- Transparent fees and cancel-anytime terms.
- Itemized work, not vague "sweeps."
- Realistic timelines and no guarantees.
- Local fluency: bilingual support and familiarity with regional lenders.
Costs, timelines, outcomes
You'll typically see an upfront onboarding fee and a monthly service range that fits the scope of work. Light cleanups can show traction in 60 - 90 days; complex identity-theft or mixed-file cases can run 6 - 12 months. Results vary by evidence and creditor response speed. Small pause: numbers are only part of the story.
A Miami moment
One afternoon near Flagler Street, a nurse sat with a counselor from a local office. Over cafecito, they pulled her three reports, spotted a medical collection paid last year, and drafted a targeted furnisher dispute with her receipt attached. Not dramatic, just diligent - and within a cycle, the update posted.
How to prepare before calling
- Pull your free credit reports and note every negative item with dates and balances.
- Gather proof: payment receipts, settlement letters, identity-theft affidavits.
- Set a timeline goal (mortgage in nine months? car refi?).
- Decide a budget and how you'll measure progress monthly.
- Check consumer complaints and reviews; look for consistent, specific feedback.
- Ask for sample dispute language they use and how they escalate.
- Confirm bilingual service if needed and local lender insight.
DIY or hire?
If your file has a few clean-cut inaccuracies, you can dispute directly with bureaus and furnishers, maintain low utilization, and add a small installment builder. Hire help when time is tight, documentation is messy, or issues involve mixed identities, medical billing layers, or repeated reinsertions. A steady, organized advocate can pay for itself in avoided mistakes.
Expectations that keep you in control
- Define milestones: clean personal info across all bureaus, then tackle highest-impact items.
- Track bureau responses every 30 - 45 days; keep a folder with all letters.
- Rebuild while you repair: one secured card or builder loan; keep utilization under 10 - 30%.
- Avoid buying tradelines or "quick score hacks." Risk high, payoff uncertain.
- If a mortgage is on deck, minimize new inquiries 3 - 6 months before applying.
Miami's credit landscape moves fast, but your plan shouldn't. Choose steady guidance, insist on documentation, and measure progress month over month. With patience and proof, you can trade short-lived fixes for lasting credibility.
So wherever you need help, we are here to offer our credit repair service. 007 Credit Agent is the leader in Miami for credit repair services. Please contact us ...
114 results for Credit Repair Services near Miami, FL. Show BBB Accredited only. Sort By Distance. Distance Rating.
MIAMI CREDIT REPAIR, 10511 SW 40th St, Miami, FL 33165, 5 Photos, Mon - 9:00 am - 5:30 pm, Tue - 9:00 am - 5:30 pm, Wed - 9:00 am - 5:30 pm, Thu - 9:00 am ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.